I PAID OFF MY HUSBAND'S $300,000 BUSINESS DEBT—THE SHAREHOLDER AGREEMENT MY LAWYER MADE HIM SIGN THREE YEARS EARLIER WAS THE ONLY THING THAT SAVED ME THE NIGHT HE INTRODUCED HIS GIRLFRIEND
I PAID OFF MY HUSBAND'S $300,000 BUSINESS DEBT—THE SHAREHOLDER AGREEMENT MY LAWYER MADE HIM SIGN THREE YEARS EARLIER WAS THE ONLY THING THAT SAVED ME THE NIGHT HE INTRODUCED HIS GIRLFRIEND
The morning I wired the final payment that cleared my husband's business debt, I thought I was walking into the happiest day of my marriage. Instead I walked into a living room where he'd already invited his girlfriend to sit on our couch and told me to pack my things. What he'd forgotten, or maybe never fully understood, was the paperwork his own desperation had made him sign three years earlier.
My name is Renata Solberg, and for the better part of a decade I built a modest but steady career as an independent financial consultant, mostly helping small manufacturing and logistics companies clean up their books before loan renewals or acquisitions. My husband, Callum Voss, ran a mid-sized freight and trucking company called Voss Transit Solutions, a business his father had started and that Callum had expanded, a little too aggressively, into refrigerated hauling right before diesel prices spiked and two of his largest retail contracts renegotiated their rates downward within the same six-month window. By the time he came to me, visibly panicked, the company was roughly ninety days from defaulting on its senior credit line, and the bank had already signaled they weren't interested in extending further credit without a substantial capital injection and stronger covenants than Callum's existing agreement had ever required.
I want to be honest that I didn't hand over money that first time out of blind trust. I'd spent enough years reviewing distressed companies professionally to know that rescuing a failing business with personal funds, especially a spouse's business, without proper legal protection is one of the most common ways people lose both their savings and their marriage in a single stroke. So when I agreed to use roughly a hundred and twenty thousand dollars from the sale of a condominium my grandmother had left me, along with a commitment to keep covering the remaining debt service through my consulting income, I insisted we bring in an actual corporate attorney rather than relying on the discount lawyer Callum's father had always used for the company's routine paperwork. My college friend Priya Nakamura, who by then specialized in small business recapitalization work, drafted what she called a secured investment and recapitalization agreement, which converted my cash injection into preferred shares in the company, shares that carried a specific protective clause: if the underlying bank debt wasn't fully retired through the company's own operating revenue within a defined window, my preferred shares would automatically convert into common shares representing majority voting control.
Callum signed it without much complaint at the time, mostly because he was desperate and mostly, I think now, because he assumed the debt would obviously get paid off through the business itself long before any conversion trigger mattered. Priya had built the clause in precisely because she'd seen too many cases where a spouse quietly absorbed years of personal financial sacrifice while the underlying business never actually recovered its own footing, leaving the rescuing spouse with nothing to show for it besides an empty bank account and a company that limped along exactly as fragile as before.
That's essentially what happened over the following three years, though it took me longer than I'd like to admit to see the full pattern. The company's revenue did improve somewhat, enough that Callum stopped drawing on the emergency line of credit, but the actual bank loan itself never got paid down through company earnings the way we'd originally hoped. Instead, month after month, I found myself the one transferring funds from my consulting income directly to the loan servicer, while Callum told me repeatedly that the business needed to reinvest its own cash flow into fleet maintenance and driver retention rather than accelerating debt repayment. I believed him, mostly because I wanted to, and because contradicting him always led to arguments about how I "didn't understand operations" the way he did.
About eight months before the loan was finally retired, I started noticing financial irregularities that had nothing to do with fleet maintenance. As a preferred shareholder under our agreement, I had contractual rights to quarterly financial disclosures, something Priya had also insisted on including, and going through one of those disclosure packets I noticed a series of corporate credit card charges that didn't match any category I recognized: two separate boutique hotel stays in a city where the company had no operations, recurring charges from a jewelry store, and a monthly lease payment routed through the company's accounts payable to an apartment complex I'd never heard mentioned in any business context. I hired an independent bookkeeper, someone with no personal connection to Callum, to trace the charges properly, and within about three weeks she confirmed what I'd already started to suspect. The apartment lease was in the name of a woman named Brielle Calloway, and the pattern of hotel stays and jewelry purchases lined up almost exactly with dates Callum had told me he was traveling for supplier meetings.
I didn't confront him the moment I found this out. I want to be honest about why, because I don't think the reason reflects particularly well on me in hindsight: I was six weeks from finally clearing the loan balance entirely, and some exhausted, stubborn part of me wanted to finish what I'd started, to actually see the debt reach zero after three years of sacrifice, before I let myself deal with what the discovery meant for our marriage. I called Priya instead, told her everything, and she immediately flagged that the misuse of corporate funds for personal expenses, on top of everything else, was itself a breach of the operating covenants in our recapitalization agreement, separate from anything relating to fidelity, and that once the loan was paid off and my preferred shares converted, I'd have clear legal standing to address both issues as majority owner.
The final payment cleared on a Tuesday morning, and Priya filed the conversion certificate with the state that same afternoon, formally confirming what the original agreement had always promised: as of that date, I held majority voting control of Voss Transit Solutions. I didn't come home that evening with champagne. I came home because Callum had texted me that morning asking me to be there for a family dinner, phrased vaguely enough that I assumed it was some kind of belated celebration his parents had organized.
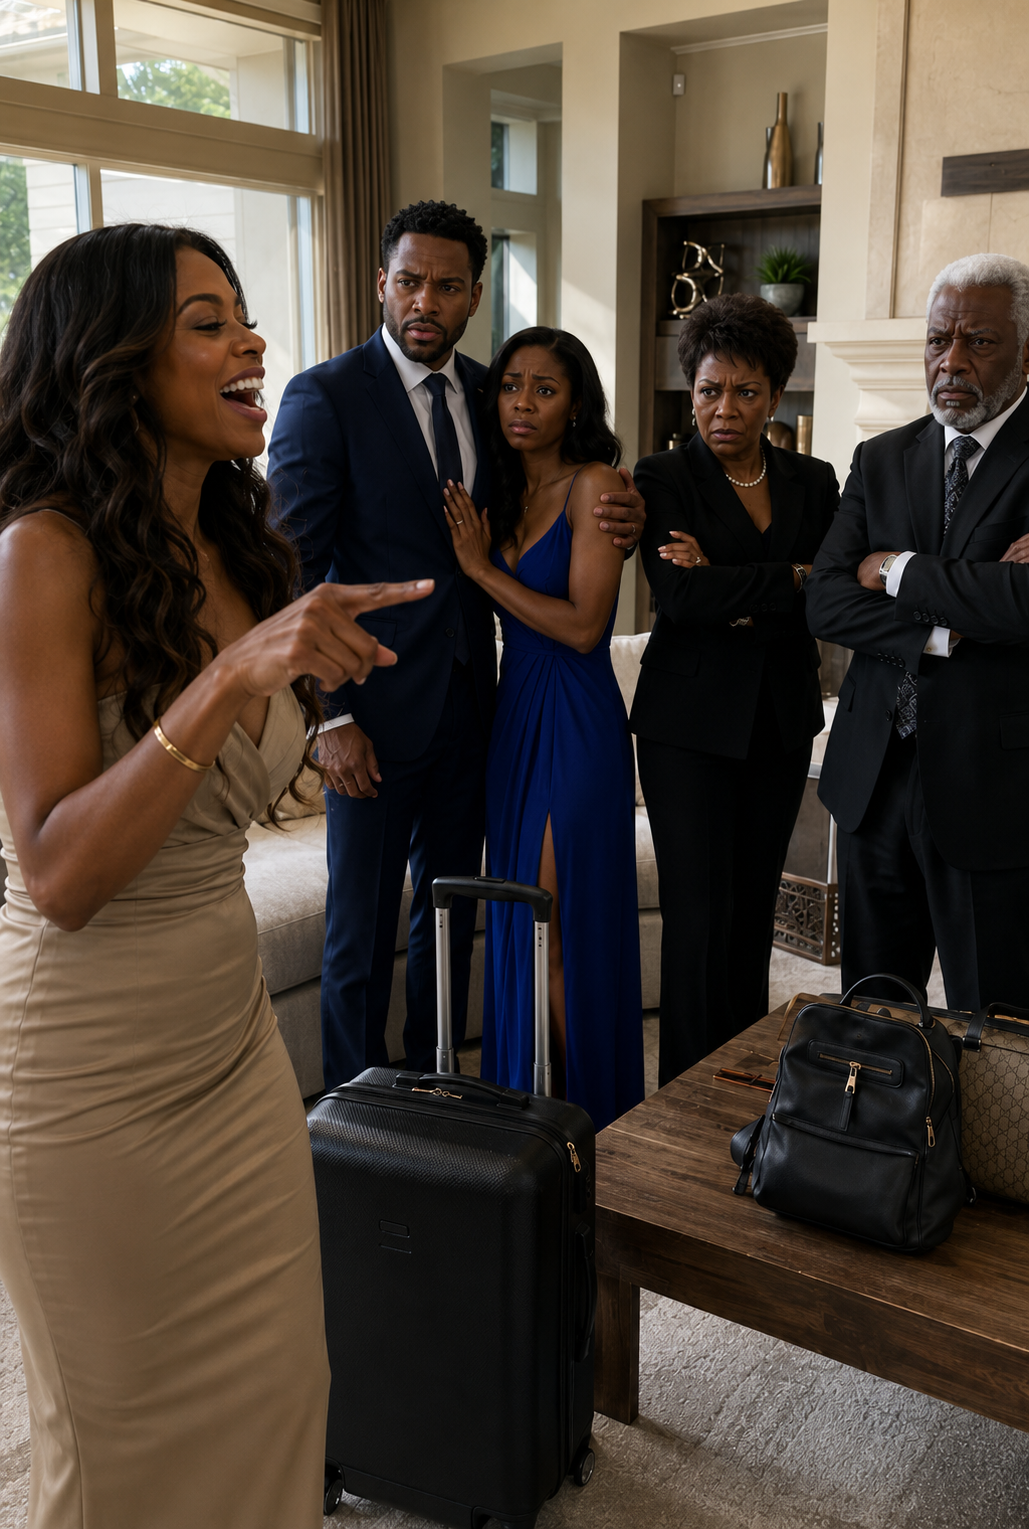
What I walked into instead was a living room where Callum sat beside a young woman I recognized immediately from the bookkeeper's research, her arm draped along the back of the sofa with a familiarity that told me this wasn't a first meeting for anyone else in the room. His parents, Marguerite and Desmond, sat across from them with expressions that made clear they already knew exactly what this dinner was for. Callum stood, and with a calm that genuinely unsettled me more than shouting would have, told me that today was "a special day" for an entirely different reason than the one I'd spent three years working toward. He introduced Brielle as someone he'd been seeing for almost a year, told me it was time I moved out, and said his parents agreed that he deserved "someone who understood his ambitions better." Marguerite, without much hesitation, added that I'd "never really fit into the family's vision" for Callum's future.
I want to be honest that even having already suspected the affair for months, hearing it stated so plainly, in front of his parents, in the home we'd shared, still landed like a blow I wasn't fully braced for. I didn't laugh, and I didn't scream. I sat down, opened the folder I'd brought with me, and told them, as steadily as I could manage, that before anyone discussed who was leaving the house, there were two documents everyone in that room needed to actually read.
The first was the conversion certificate Priya had filed that afternoon, confirming my majority ownership of the company. Callum's face went through several stages of confusion before landing on something closer to panic as he registered what the document actually said, and when Desmond insisted I must be misunderstanding some technicality, I reminded him that Priya had walked Callum through every clause of the original agreement three years earlier, in a meeting Desmond himself had actually sat in on, back when the company's survival mattered more to everyone than it apparently did now. The second document was a formal notice, executed that same morning by written shareholder consent as permitted under the company's own bylaws, removing Callum as chief executive officer effective immediately and appointing an interim CEO, a longtime operations manager named Grant Hollis whom I'd already spoken with privately about stepping into the role.
Brielle, to her credit, looked increasingly uncomfortable as the actual scope of what Callum had told her began to unravel in real time. She asked him, quietly at first and then with more edge, whether he'd told her the truth about being the company's owner and chief executive, and when he didn't answer, she asked again, louder, clearly realizing that whatever picture he'd painted of his life for her had very little basis in the paperwork now spread across the coffee table.
I told them, as plainly as I could, that the house we were sitting in had also been purchased three years earlier through a real estate holding entity that was itself a subsidiary of the company, structured that way originally for depreciation and tax purposes on Priya's advice, which meant that, strictly speaking, majority control of the parent company also gave me control of that holding entity. I was careful to add, because it was true and because I didn't want to overstate what any of this actually meant in the moment, that since the house had also functioned as our marital residence, any question of who could continue living there while our divorce proceeded would ultimately need to go through family court rather than being something I could simply declare on my own that night. I wasn't interested in making a dramatic point about ownership if it meant misleading anyone about how the law actually worked.
The months that followed were considerably less cinematic than that dinner, in the way real legal processes usually are. Callum, through a hastily retained attorney, initially challenged the validity of the conversion clause, arguing he hadn't fully understood its implications when he signed it under financial duress. Priya's response was straightforward: the agreement had been reviewed line by line in a recorded meeting years earlier, with his own father present, and duress claims are difficult to sustain when a party had access to independent counsel and simply chose not to use it carefully. A county court ultimately upheld the conversion as valid after a hearing that took the better part of four months to schedule and resolve, considerably longer than anyone in that living room would have guessed watching the documents get laid on the table that first night.
The misuse of corporate funds took a separate track entirely. Once Grant and the company's outside auditor completed a full review, they identified just over forty thousand dollars in personal expenses Callum had charged to company accounts over roughly a year and a half, covering the hotel stays, jewelry, and Brielle's apartment lease. The board, now operating under my majority control, chose to pursue this as a civil matter rather than referring it for criminal prosecution, mostly on Priya's advice that a criminal fraud case would be difficult to prove beyond a reasonable doubt given how the expenses had been coded, and that a civil repayment demand attached to his eventual severance negotiation was more likely to actually recover the funds. Callum ultimately agreed, as part of a broader settlement resolving both his removal and the fund misuse, to repay the full amount from his remaining minority equity stake in the company, shares he retained from before the conversion but which now carried no operational control whatsoever.
Our divorce, running on its own separate timeline, resolved with the marital home issue settled through mediation rather than a contested hearing, once it became clear that the property's corporate ownership structure limited how much of it could realistically be argued as a shared marital asset in the traditional sense. Callum moved out within a negotiated sixty-day transition period, and I bought a smaller house on my own about four months later, a decision that felt less like defeat and more like simply choosing not to keep living inside a story that had never been quite what I'd believed it was.
Brielle didn't stay with Callum much past that first month, according to a mutual acquaintance who mentioned it to me almost apologetically at a industry conference the following spring. Apparently the version of his life he'd described to her bore little resemblance to what she found once the company records, the settlement, and the divorce proceedings made the actual situation impossible to ignore. Callum, last I heard, took a regional sales role at a competing logistics firm, a considerable step down from running his own company, though I try not to spend much energy tracking the specifics of how that's gone for him.
Voss Transit Solutions, under Grant's leadership and my continued majority ownership, stabilized within about a year, eventually renegotiating better terms on its remaining credit lines now that the covenant violations and leadership instability were behind it. I still think, sometimes, about how close I came to losing everything I'd worked toward simply because I trusted a promise instead of insisting on paperwork, and I'm grateful, in a complicated way, that some cautious, unromantic part of me three years earlier had the sense to ask a lawyer to write down what "partnership" was actually supposed to mean, long before I had any real reason to think I'd ever need it.
HE FIRED HIS WIFE IN FRONT OF THE ENTIRE ICU — HE DIDN’T KNOW HER NAME WAS ON THE HOSPITAL’S DEED
HE FIRED HIS WIFE IN FRONT OF THE ENTIRE ICU — HE DIDN’T KNOW HER NAME WAS ON THE HOSPITAL’S DEED
Every monitor in the intensive care unit kept beeping steadily while Dana Okafor stood motionless, watching her husband rip her badge from her scrubs in front of a room full of nurses she’d trained herself. Preston Calloway had no idea that the woman he’d just ordered security to escort out owned the controlling stake in the building he worked in — and he was about to find out in the worst possible way, in front of the one audience he could never talk his way past.
Dana had spent eleven years at Ridgeline Medical Center in Portland, most of them in the ICU, working nights so she could be home during the day when her daughter, Iris, was small. She’d started nursing school at twenty-six, later than most, after six years of putting her own plans on hold to care for her father, Walter, through end-stage liver disease. She’d been three semesters into a pre-med track before his diagnosis; she left it behind without much ceremony, because there hadn’t been anyone else willing to sit with him through the dialysis, the infections, and the long nights when the pain medication wasn’t quite enough.
She met Preston during those years, when he was a junior administrator doing rotations through the same hospital where her father was treated. He was attentive and ambitious, and he told her more than once how much he admired her devotion to her father, a compliment she believed for a long time meant something more than it eventually turned out to.
They married in a small ceremony on Whidbey Island, her father walking her down the aisle from his wheelchair, thin but lucid enough to grip Preston’s arm before letting go of her hand. “Take care of her,” Walter had said. Preston promised he would. Walter had studied his face for a long moment without smiling, the way a man studies a signature he’s not sure he trusts yet.
After Walter died, Dana threw herself into work and into raising Iris, now seven, while Preston climbed steadily through hospital administration. She quietly caught errors in his budget proposals more than once and never mentioned that two of his more well-regarded departmental reports had actually started as her notes on a legal pad at the kitchen table. His mother, Marguerite, made a habit of reminding Dana over holiday dinners that nursing was “certainly respectable, if not exactly a leadership track,” and Dana had learned to smile and change the subject rather than argue.
Then came Bianca Reyes, a nurse manager hired eighteen months earlier who started appearing beside Preston at board dinners and out-of-town conferences that had nothing to do with her department.
The firing
The morning it happened, Dana was finishing a med pass on a post-cardiac patient when Preston walked into the ICU with hospital security trailing behind him, which should have told everyone in the room this wasn’t spontaneous.
“You’re done, Dana,” he said, loud enough for the nurses’ station to hear clearly. “You’re not to set foot in this building again.” He pulled the badge clip from her scrub top hard enough that the lanyard snapped.
Marguerite watched from the doorway with an expression she wasn’t bothering to hide. Bianca stood beside her. “Maybe now this department can finally modernize,” Bianca said. “Some people have been here so long they think the place can’t run without them.”
Dana didn’t cry, and she didn’t argue. She bent down, picked up the badge from the floor, and put it in her pocket. She checked on Mr. Alvarez in bed 4 before she left, adjusting his blanket and telling him Nurse Priya had his chart and knew every medication on it, and then she walked to the elevator while Preston watched with an expression that looked almost proud of himself.
What he didn’t know was that she was carrying, in the bottom of her bag, a sealed envelope her father had given her six years earlier with instructions not to open it until she was certain of who around her had shown their true character.
What was in the envelope
Sitting in her car in the parking garage, rain starting against the windshield, Dana finally broke the seal. Inside was a card with a phone number and a single line: Call Randall Osei. He’s been protecting what was always yours. Sign nothing.
Randall Osei turned out to be an estate attorney in his sixties who told her, once she identified herself, that he’d been waiting six years for this call. Her father, it turned out, hadn’t just been an accountant for a regional pharmaceutical distributor, which was the story he’d let most people believe. Over three decades he’d quietly acquired stakes in small clinics, medical office buildings, and eventually a controlling interest in Ridgeline Medical Center itself, all of it structured through a holding entity called Meridian Health Partners, and all of it placed into an irrevocable trust naming Dana as successor beneficiary, with instructions that the trust remain dormant and unpublicized until she chose, or was forced by circumstance, to activate it.
“He wanted to know who’d stay beside you without knowing what you’d eventually inherit,” Randall explained. “He had concerns about Preston’s ambition even before the wedding. That’s why the trust sat quiet this long.”
Randall also had something less comfortable to show her. Ridgeline’s board had recently approved a $210 million expansion, financed partly through Meridian’s approval as majority stakeholder, and the authorization signature on file, purportedly Dana’s, wasn’t hers. A forensic document examiner Randall had already consulted confirmed the handwriting was a close but ultimately inconsistent match.
“Someone forged my signature to push through a construction deal,” Dana said.
“We don’t yet know who physically produced it,” Randall said. “But someone acting on the project’s behalf did. From here forward, don’t confront him, don’t sign anything, and keep every document, message, and financial record you come across.”
What the investigation turned up
Over the following weeks, Dana and Randall’s firm found a credit account opened in her name with an outstanding balance just over $85,000, mostly luxury purchases she’d never made — the kind of paper trail, Randall explained, that would look devastating in a custody filing describing her as financially unstable. A contact in Ridgeline’s records department quietly passed along a copy of the expansion authorization with the forged signature on the final page.
Bianca showed up at Dana’s house not long after, unprompted, and got straight to it. “I know you control Meridian,” she said. “Approve the expansion, give me a formal role in the project, and I’ll make sure Preston keeps the divorce simple.”
“And if I don’t?”
“Then the board hears a very different version of you. Financial instability, an abandoned nursing position, and a discrepancy in the ICU medication logs from your last shift that can be made to look a lot worse than it actually was.”
“I never mishandled medication.”
“The truth matters less once someone’s already built a different one,” Bianca said.
Dana’s phone was recording the entire conversation from the coffee table. She said no. Bianca told her, without much emotion, that they were now at war.
That evening Preston filed for divorce and sought sole custody of Iris, describing Dana in the petition as emotionally unstable and financially reckless, citing her termination and the fabricated debt as evidence. Reading the custody section, Dana’s hands weren’t steady, but her decision was: he could have the house, the accounts, all of it. He would not get their daughter.
The board meeting, not a gala
Randall’s firm had already been quietly documenting the forged signature, the fraudulent credit account, and Bianca’s recorded threat, and timed the disclosure for Ridgeline’s quarterly board meeting, where Preston was scheduled to formally present the expansion for final sign-off, with Marguerite attending as a longtime hospital donor and Bianca present as the newly appointed project liaison.
Dana walked into the boardroom in a plain gray suit, a folder under her arm, and took a seat near the back without announcing herself. Preston was mid-presentation, gesturing at renderings of a new surgical wing, when the board chair interrupted to note that, per bylaws, the annual confirmation of Meridian Health Partners’ controlling beneficiary needed to be read into the record before any capital project could be ratified.
“Meridian confirms Dana Okafor as successor beneficiary and controlling majority owner of Ridgeline Medical Center,” the chair read aloud.
The room went quiet. Preston’s expression didn’t recover quickly.
Dana stood. “A few weeks ago, my husband had me removed from this hospital in front of the entire ICU staff and told me I’d never belong here again.” She looked at him directly. “It was never his to decide.”
Randall stepped forward with a forensic document examiner, who displayed Dana’s verified signature beside the forged authorization on a projector screen, the discrepancies highlighted in red. “Our investigation also recovered internal emails directing hospital staff to open financial accounts under Mrs. Okafor’s name without her knowledge,” Randall said.
Preston turned to Bianca. “Tell them this isn’t what it looks like.”
Bianca didn’t. “I have the messages,” she said instead. “He told me to delete several of them. I’m not protecting anyone at this point.”
Two investigators from the state’s healthcare fraud division, whom Randall had looped in a week earlier once the forgery was confirmed, were waiting outside the boardroom. The board voted unanimously to suspend Preston’s administrative credentials pending a full audit, and revoked his building and systems access before he’d finished gathering his laptop.
Marguerite stood, indignant. “My son helped build this hospital’s reputation.”
“Your son forged a document inside a hospital my father actually built,” Dana said. There was no triumph in her voice, just fact.
How it resolved
The state’s investigation confirmed the forged authorization and the fraudulent credit account, and Preston was charged with forgery and identity theft; he pleaded guilty to reduced charges roughly eight months later in exchange for restitution and eighteen months of probation, along with a permanent loss of his hospital administrator license. Bianca cooperated with investigators in exchange for immunity from the more serious charges, though she lost her nursing position and relocated out of state shortly after.
The family court, presented with the documented pattern of financial manipulation and coercion underlying Preston’s custody claims, rejected his petition for sole custody entirely and granted Dana primary custody, with Preston receiving standard supervised visitation reviewed after a year. Dana never blocked his relationship with Iris beyond what the court required, even when it would have been easier to.
Months later, Marguerite came to Dana’s office, quiet in a way she’d never been before. “I was wrong about you,” she said. “I thought my son’s title made him more valuable than the people actually holding this place together.”
“My father used to say you learn who someone is by watching how they treat people who have nothing to offer them,” Dana said. She didn’t forgive everything in that sentence, but she let Marguerite start rebuilding a slow, boundaried relationship with Iris rather than shutting the door entirely.
As the new controlling stakeholder, Dana canceled the oversized expansion Preston had pushed through fraudulently and redirected the capital toward a community maternal-health clinic in the hospital’s east wing, along with raised nurse staffing ratios and a tuition assistance program for hospital staff pursuing further education, the kind of program she wished had existed when she’d left her own pre-med track years earlier.
Three years later, using that same tuition program, she finished the medical degree she’d set aside to care for her father, attending night classes while working days and still making time for Iris’s soccer games. Iris was the first person to hug her after her white-coat ceremony. “Grandpa always said you were already a doctor,” she told her mother. “You were just missing the piece of paper.”
In Ridgeline’s lobby now hangs a small photograph of Walter Bennett, and beneath it a plaque that reads simply: He watched quietly to see who stayed kind when they thought no one important was looking. Dana still thinks, sometimes, about the afternoon she stood in a parking garage in the rain with a badge in her pocket and an envelope she hadn’t yet had the courage to open. Preston had wanted to prove she didn’t belong in that hospital. Instead, he’d handed her the reason to finally claim it.