THREE DAYS AFTER MY C-SECTION, MY HUSBAND CHANGED THE LOCKS AND FLEW HIS FAMILY TO CABO — HE NEVER READ THE TRUST DOCUMENT THAT SAID THE HOUSE WASN’T HIS TO LOCK ME OUT OF
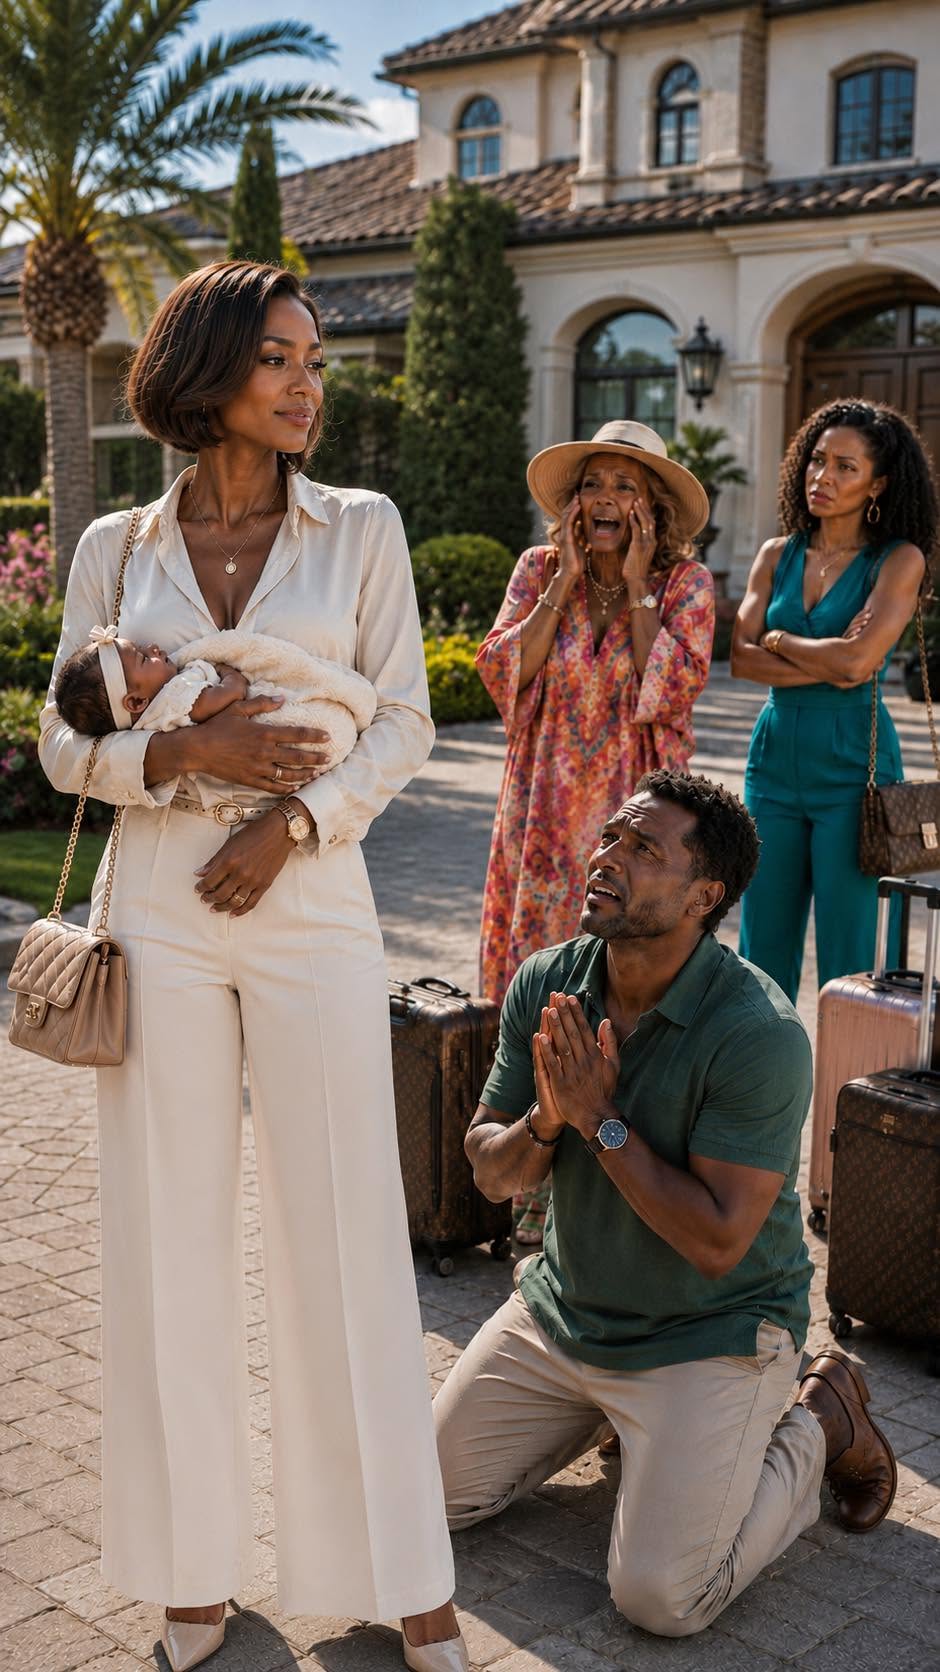
THREE DAYS AFTER MY C-SECTION, MY HUSBAND CHANGED THE LOCKS AND FLEW HIS FAMILY TO CABO — HE NEVER READ THE TRUST DOCUMENT THAT SAID THE HOUSE WASN’T HIS TO LOCK ME OUT OF
She came home from the hospital still bleeding through her incision, carrying a five-pound daughter who hadn’t slept longer than forty minutes at a stretch, and found a locksmith’s business card taped to a door that no longer opened for her key. What she found out three weeks later, buried in a bank’s fraud department file, was so much worse than a changed lock.
The Keypad That No Longer Knew Her
Delphine Achebe-Ryland had been discharged from Denver Health at 4:40 in the afternoon, eleven days post-due-date, three days post-C-section, still moving like her body had been folded in half and put back together with staples. Her daughter, Ada, was asleep in the car seat carrier, and Delphine’s mother had driven them both home because Delphine’s husband, Preston Ryland, had texted that morning that “something came up with work” and he’d meet her at the house.
The house on Sable Ridge Court had belonged to Delphine’s grandmother, Odessa Achebe, who had raised Delphine from age nine after her parents died in a car accident on I-70. When Odessa passed four years earlier, she hadn’t simply willed the house to Delphine outright. She’d set it up through a testamentary trust drafted by her longtime attorney, a meticulous man named Harold Ferris, because Odessa had watched two of her own sisters lose houses in bad marriages and had told Delphine, more than once, “This house skips whoever you marry. It goes to you, and only you, until you tell Harold otherwise.”
Delphine had never told Harold otherwise.
She stood on the porch with the carrier in one hand and her mother steadying her other elbow, and typed the code into the smart lock. The screen blinked, then read: Access Denied — Contact Primary Account Holder.
“That’s strange,” Delphine said, and typed it again.
Denied.
Her mother frowned. “Try it slower.”
Denied again.
Delphine called Preston. It rang four times before he picked up, and behind his voice she could hear an airport boarding announcement — not construction noise, not an office, an actual gate agent calling zone two for a flight to Los Cabos.
“Preston, the lock isn’t taking my code.”
“Yeah, I updated the app this morning. I meant to text you.” He didn’t sound apologetic. He sounded like a man reading a menu. “Listen, my mom’s flight got moved up and Kayla wanted to leave a day early too, so I’m heading to Cabo with them. I’ll sort the lock out when I’m back.”
Delphine’s mother, hearing this on speaker, went very still.
“You’re leaving the country,” Delphine said, “three days after I had surgery.”
“You have your mom there. You’re fine.” A pause, then, quieter, like he was stepping away from the gate: “Honestly, Delphine, my mom thinks it’s better if you two get some space anyway, after everything with the trust stuff. She said you’ve been acting like you own the place since Grandma died.”
“I do own the place, Preston. That was never a secret.”
“Well, maybe stop rubbing it in people’s faces,” he said, and the call ended.
A Trust Older Than the Marriage
Delphine did not cry on the porch. She had learned, over eleven years of being an only grandchild raised by a woman who ran a beauty-supply distribution company by herself after being widowed at forty, that crying in front of an audience rarely fixed anything.
She and her mother drove to her mother’s condo instead, and once Ada was fed and asleep in a borrowed bassinet, Delphine called Harold Ferris, the trustee.
“I need to know exactly what authority I have over who occupies the Sable Ridge house,” she said.
Harold, seventy-one and unbothered by drama, pulled the file while they spoke. “Your grandmother’s trust names you as sole beneficiary with a lifetime right of occupancy. Your husband has never held title. He’s been living there at your discretion, as your spouse — nothing more. That discretion is yours to grant or revoke. It always has been.”
“He changed the locks on me.”
There was a pause on Harold’s end that told Delphine he understood the weight of what she’d just said better than most people would.
“Then as trustee, I have standing to protect the beneficiary’s occupancy rights,” Harold said. “I can have the locks re-secured under your sole access again, and I can have a formal notice sent revoking any implied permission he had to remain there. If he’s out of state, this is actually the cleanest possible time to do it.”
“Do it,” Delphine said.
The Loan No One Told Her About
The locksmith came the next morning, working from a letter Harold had drafted on trust letterhead. But it was two days later, while Delphine was setting up a bill-pay transfer from the joint checking account to cover Ada’s pediatrician deposit, that she noticed something that had nothing to do with the locks at all.
A wire transfer, $47,500, had gone out of the joint account nine days earlier — two days before her due date — to an entity called Highline Bridge Capital LLC. Delphine didn’t recognize it. She called the bank’s fraud line more out of confusion than suspicion.
The representative, a woman named Corinne, put her on hold for six minutes and came back sounding careful.
“Mrs. Ryland, that wire was disbursement from a personal loan — a $65,000 signature loan taken out against the equity in a property listed as collateral. The application lists 3140 Sable Ridge Court as jointly owned by you and Preston Ryland, with your notarized signature on the deed of trust rider.”
Delphine’s mouth went dry. “I never signed anything. I don’t own that house jointly with anyone. It’s held in a trust.”
“There’s a notary stamp and signature dated six weeks ago,” Corinne said. “I can see it right here in the loan file.”
“I was seven months pregnant six weeks ago and I have never been to a notary with my husband in my life.”
Corinne’s tone shifted into the flat, procedural register of someone who had just heard the sentence that turns a phone call into a case file. “Ma’am, I’m going to flag this account for suspected fraud immediately and freeze further disbursement. You’ll need to file a police report and we’ll need a signature comparison. Do you know who notarized this?”
Delphine looked at the name printed under the stamp.
Kayla D. Ryland, Notary Public, State of Colorado.
Her husband’s sister.
What the Bank Noticed
The fraud investigation moved faster than Delphine expected, mostly because Preston had been sloppy. Kayla, it turned out, had gotten her notary commission eighteen months earlier to help with paperwork at the property management company where she worked, and Preston had asked her to notarize “a quick refinancing thing” while Delphine was at a prenatal appointment, telling Kayla that Delphine had already signed and just needed the notarization logged for the file. Kayla had stamped it without requiring Delphine to appear in person — a violation of Colorado notary law that, once reported, put Kayla’s own commission and employment at risk.
The $47,500 that had already gone out had been wired again, two days later, from Highline Bridge Capital to a company called Vantage Sportsbook Partners, which Denver Police’s financial crimes detective, a woman named Ines Calloway, identified within an afternoon as a licensed but aggressive online sports betting platform. Preston had lost most of it within a week, chasing football parlays while telling his mother and sister he was “handling an investment opportunity.”
Detective Calloway explained it to Delphine plainly over the phone: “Forging a signature to secure a loan, and using a notary to falsely certify that signing occurred in person, is felony forgery under Colorado law, and depending on how the DA’s office wants to charge it, potentially fraud by check or securing property by deception given the sports betting destination of the funds. Your sister-in-law is exposed too, for false certification, though prosecutors often treat that differently if she cooperates and testifies she didn’t know it was fraudulent.”
“What happens to the loan?” Delphine asked.
“Since the collateral document listing you as co-owner was forged, the lender’s claim against the house is void. You’re not liable for the debt. The lender will have to pursue Preston personally, and likely write most of it off as unsecured, since he’s already spent it.”
Cabo Ends Early
Preston found out the locks had changed when his mother, Deborah, tried to log into the smart-lock app from Cabo to “check the mail schedule” and discovered her account access had been removed entirely. He found out about the fraud investigation twenty minutes later, when Detective Calloway called his cell phone directly to schedule an interview.
He flew back three days early, alone — Deborah and Kayla stayed in Cabo, Deborah reportedly furious that the “family trip” was being cut short over what she called, to anyone who’d listen, “a misunderstanding about paperwork.”
Preston showed up at Delphine’s mother’s condo instead of the house, because the house no longer recognized his phone, his key, or his face on the exterior camera he’d once used to check on deliveries.
“You called the cops on me,” he said when Delphine came outside to the parking lot, Ada asleep against her mother’s shoulder inside.
“I called the bank when I saw money missing from an account with my name on it,” Delphine said. “The bank called the fraud unit. The fraud unit is the one who found your sister’s stamp on a signature I never made.”
“I was going to pay it back before you even noticed.”
“You gambled away almost fifty thousand dollars nine days before I had major surgery, using a forged document that put a lien on a house that isn’t even legally yours to put a lien on,” Delphine said. “There’s no version of that sentence where you were handling it.”
Preston’s voice cracked into something closer to panic than anger. “You’re going to let them charge my sister? She was just helping me.”
“She notarized a signature that was never made in front of her. That’s not helping. That’s a felony, and I didn’t put her name on it — you did.”
The House That Stayed Hers
Preston was charged three months later with felony forgery and criminal impersonation; his attorney negotiated a plea to a single reduced count in exchange for full cooperation in the fraud case and an agreement to pay restitution to the lender for the outstanding balance, since the lender’s claim against Delphine’s house had already been voided by the court once the forgery was established. He avoided jail time in exchange for probation, mandatory financial counseling, and the restitution order — a resolution Detective Calloway told Delphine was fairly typical for a first-time offense involving family collateral rather than a stranger victim. Kayla lost her notary commission and her job at the property management company, but avoided charges after cooperating fully and testifying that she’d been misled about the circumstances of the signing.
The divorce was uncontested on the property question, since there had never been anything to contest — the trust made that simple in a way Delphine hadn’t fully appreciated until she needed it to be. Custody was resolved through standard mediation; nothing in the fraud case touched Preston’s fitness to see his daughter, so they settled into a routine co-parenting schedule once he’d stabilized, supervised at first by mutual agreement while he worked through the gambling counseling the court had ordered.
Delphine never sold the house. She had Harold amend the trust’s occupancy terms so that no future spouse would ever again be granted access without a separate, explicit written agreement — a clause her grandmother, she suspected, would have found both sad and completely unsurprising.
May you like
On a quiet Saturday morning eight months later, Delphine stood in the nursery she’d repainted a soft ochre yellow, watching Ada nap in the crib by the window, and thought about how strange it was that the version of the story people would have expected — the locks, the lockout, the vacation, the outrage — had barely mattered in the end. What had mattered was a trust document written by a woman who’d buried a husband young and refused to let history repeat itself in her granddaughter’s marriage, and a bank employee named Corinne who’d taken six minutes on hold seriously enough to ask the right question.
The house had never really been at risk. Delphine just hadn’t known, until she needed to, how thoroughly her grandmother had already protected it.